How to Choose the Right Personal Loan Advisor in Malaysia
Deciding to use a personal loan advisor is one thing. Picking the right one is a separate decision — and it matters more than most people expect, since a rushed or poorly-matched application can leave a mark on your credit file that follows you into your next application, too.
If you've already decided you want guidance instead of applying blind, here's what actually separates a personal loan advisor worth working with from one who's just pushing paperwork through.
What a Good Personal Loan Advisor Should Actually Be Doing
The value isn't in submitting your form faster. It's in what happens before anything gets submitted at all:
A real read of your CTOS or Experian report — not a glance, but an assessment of what an underwriter would flag
A shortlist of banks matched to your income type, since salaried and self-employed applicants get evaluated very differently
An honest read on your approval odds and likely interest rate range before you apply anywhere
Document preparation formatted the way each shortlisted bank's underwriting team actually expects it
A clear explanation of why certain banks were picked over others, specific to your file
If the first move is "let's submit and see," that's a sign of volume over strategy — and volume is exactly what damages your credit file.
Questions Worth Asking Before You Commit
"Based on my income type, which banks would you shortlist, and why?" An advisor who's actually reviewed your file should answer this specifically. A generic "we work with all banks" answer usually means the shortlisting hasn't happened yet.
"Is there anything on my credit report likely to raise a flag?" Active guarantor status, recent late payments, high card utilisation — these should come up in the first real conversation, not after a rejection.
"How many banks would you actually apply to, and why that number?" Every application is a hard inquiry. An advisor applying to two or three well-matched banks is playing a different game than one applying to ten and hoping one sticks.
"How are you compensated?" Reputable personal loan advisory services in Malaysia are typically paid by the bank upon successful disbursement — meaning your consultation and assessment should be free. Be cautious of anyone asking for payment upfront before any real credit review has happened.
Red Flags Worth Watching For
Encouraging you to apply everywhere at once. This isn't thoroughness — it's the opposite. Multiple rejections in a short window compound against you.
No mention of your CTOS/Experian report in the first conversation. If your credit profile isn't being discussed early, the groundwork likely isn't being done.
Can't explain why a specific bank was chosen for you. A real recommendation comes with reasoning tied to your profile, not a generic "this bank has good rates."
Vague or evasive answers about fees. This should be the easiest question to answer clearly, immediately.
Advisor vs. Applying Direct: When It Actually Matters
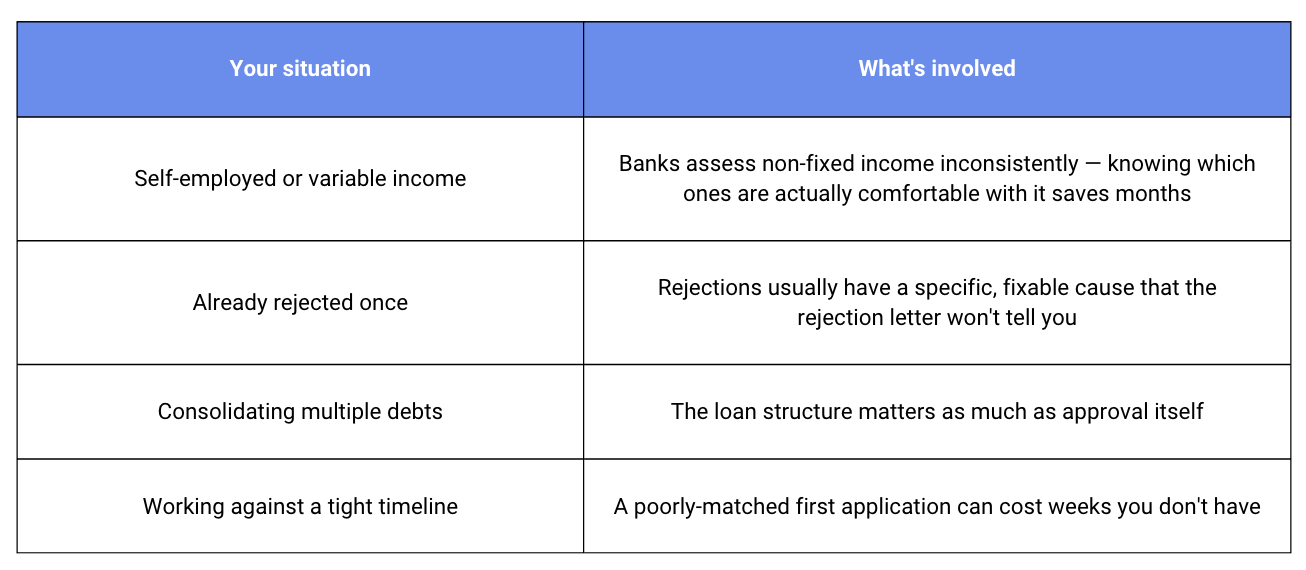
If you have a clean credit report, stable salaried income, and low existing commitments, applying directly to a bank yourself can work out fine — an advisor mostly saves you time in that case, not outcomes.
Where an advisor tends to change the outcome, not just the process:
What the Process Usually Looks Like
Credit and income review — CTOS/Experian report, existing commitments, income type
Bank shortlisting — based on your specific profile, not a generic list
Document preparation — formatted to what each shortlisted bank's underwriters expect
Submission — to a small, well-matched set of banks
Follow-up — staying reachable if a bank comes back with conditions or questions
If any step gets skipped, it's worth asking why before your file goes anywhere.
Frequently Asked Questions
-
Transparency is the clearest signal — how they're paid, why they've picked specific banks for you, and whether they'll walk you through your credit report rather than just summarising it as "fine" or "not fine."
-
Having an initial conversation with a couple is reasonable — you're comparing how thoroughly each one actually assesses your file. Just avoid letting more than one submit real applications on your behalf, since duplicate submissions can work against you.
-
No legitimate advisor can promise this — your financial profile still has to support it. What a good one does is stop you from applying to the wrong bank for an avoidable rejection.
-
Mention it upfront. A good advisor will tell you honestly whether that bank suits your profile or whether you're likely to get better terms elsewhere — even if it's not the answer you expected.
If you're ready to see which banks actually fit your profile, FinPilot's personal loan service starts with a free assessment — no commitment required.
